Table of Contents
- • The protection shortfall formula
- • A seven-step protection-needs workflow
- - 1. Define one event
- - 2. Fix the valuation date
- - 3. List immediate capital needs
- - 4. Quantify the income gap
- - 5. Identify available resources
- - 6. Calculate and stress-test the gap
- - 7. Convert the gap into a suitable recommendation
- • Worked death-shortfall example
- • What the calculation still does not answer
- - Capital or income?
- - Level or reducing need?
- - Is the replacement period defensible?
- - Is existing cover dependable?
- - Can the client afford the solution?
- • Stress-test the answer
- • Six common exam traps
- • A reusable answer structure
CISI Financial Planning and Advice
Explore the study tools and practical exam preparation built for this course.
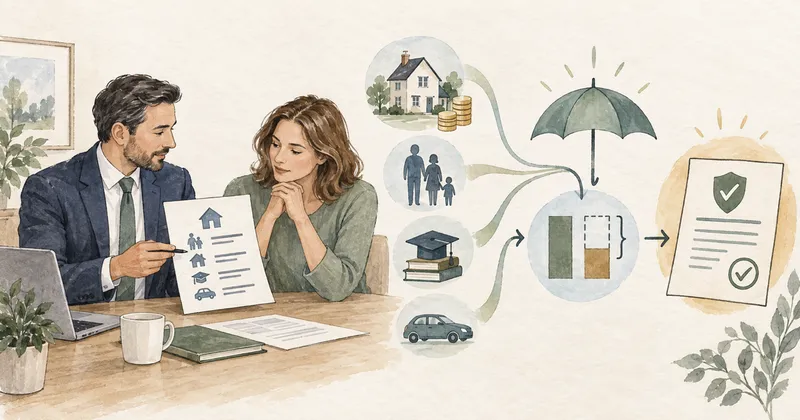
A protection shortfall calculation is useful only when it answers a precise question. “How much cover does this client need?” is too broad. The better question is: if a stated event happened now, what financial needs would arise, which resources would actually be available, and what gap would remain?
That wording prevents many of the mistakes tested in the CISI Financial Planning and Advice exam. It separates death from illness, distinguishes a capital need from an income need and stops unavailable assets from being used to make a shortfall disappear on paper.
The protection shortfall formula
Use this basic structure:
Protection shortfall = total event-specific needs − available event-specific resources
The arithmetic is simple. The judgement lies in deciding what belongs on each side.
| Needs created by the event | Resources available at the event |
|---|---|
| Debt repayment | Existing life or critical-illness cover, where applicable |
| Immediate costs and emergency reserve | Death-in-service benefit, if the client remains eligible |
| Replacement of lost household income | Relevant savings and investments intended for the need |
| Childcare, education or care commitments | Continuing earnings or benefits for the survivor |
| Adaptation, treatment or recovery costs | Other reliable, accessible event-specific resources |
Do not use the table mechanically. A pension fund available for retirement is not automatically cash available today. A family home has value but may not be usable without sale, downsizing or borrowing. A term-assurance policy may have no current surrender value but can produce a death benefit if the insured event occurs during the term.
A seven-step protection-needs workflow
1. Define one event
Start with death, serious illness or incapacity—not “protection” in general. The same household will produce different assets, benefits, costs and time horizons under each event.
2. Fix the valuation date
State that the calculation is made at a particular date. Mortgage balances, savings, earnings and employer benefits change. A calculation without a date can look precise while already being stale.
3. List immediate capital needs
These may include debt repayment, final expenses, an emergency reserve, home adaptation or a specific education commitment. Avoid adding a vague contingency merely to increase the answer; record the purpose and assumption behind every amount.
4. Quantify the income gap
Estimate the household spending that continues, subtract reliable income that survives the event and choose a justified replacement period. Use figures on the same basis. Do not compare gross salary with net household expenditure or a monthly gap with an annual benefit.
5. Identify available resources
Review existing policies, employer benefits, savings, investments, continuing earnings and benefits. Include each resource once, at the value applicable to the scenario. Check ownership, beneficiaries, term, exclusions and whether the resource is liquid enough for the need.
6. Calculate and stress-test the gap
Perform the base calculation, then ask what happens if the income-replacement period is longer, inflation is higher, an employer benefit is lost or a resource cannot be realised promptly.
7. Convert the gap into a suitable recommendation
The shortfall is an input to advice. It does not by itself choose level term assurance, decreasing cover, family income benefit, critical-illness cover or income protection. Product purpose, benefit form, term, affordability, flexibility and interaction with existing arrangements still matter.
Worked death-shortfall example
The following figures are illustrative and deliberately simplified. They demonstrate the method rather than a recommendation for a real client.
Sam and Noor have one child. If Sam died today, the fact-find supports these needs:
| Need | Amount |
|---|---|
| Repay the outstanding mortgage | £180,000 |
| Education reserve | £40,000 |
| Immediate costs and emergency reserve | £15,000 |
| Replace £30,000 annual net household income for 10 years | £300,000 |
| Total needs | £535,000 |
Resources available on Sam’s death are:
| Resource | Amount |
|---|---|
| Existing level term assurance | £150,000 |
| Savings allocated to family protection | £25,000 |
| Total available resources | £175,000 |
The initial shortfall is therefore:
£535,000 − £175,000 = £360,000
That is not yet a product recommendation. It is a quantified starting point for one defined event.
Free CISI Financial Planning and Advice Practice Questions & Exam Preview
Try 15 CISI Financial Planning and Advice practice questions from Retirement Planning
Practice CISI Financial Planning and Advice exam questions with answers and explanations. The full course includes 5 mock exams and complete syllabus coverage.
Exam Preview
Why does increasing longevity create a pension-policy challenge?
Flashcards
Why can a financial plan be useful without buying a financial product?
Focus Learn
- 1.1.1–1.1.3: planning purpose, FPSB sequence and plan components
- 1.2.1–1.2.2: permissions, engagement, ethics and competence
- 1.3.1–1.3.4: fact-finding, KYC, suitability and inconsistencies
- 1.4.1–1.4.2: streamlined advice and third-party evidence
- 1.5.1–1.5.4: financial status, scenario net worth, surplus and cash flow
- 1.6.1: agreed SMART priorities and investment objectives
- 1.7.1–1.7.5: gaps, performance, objectives, risk and tax review
1.1.1 — Purpose, roles and the continuing relationship
Financial planning connects present resources with future needs: budgeting, emergency liquidity, protection against illness and death, suitable investment, retirement and tax efficiency. It is a continuing process, while an individual piece of financial advice is a recommendation at a particular time. A useful plan may rearrange existing affairs without recommending any product. The planner remains responsible for the client relationship and delivery even when a paraplanner researches products, analyses information or drafts the document. The client supplies information, helps define priorities and makes informed decisions; agreed third-party responsibilities should be clear.
1.1.2 — The six-step FPSB cycle
Follow the sequence:…
Unlock all Focus Learn
Open every chapter’s key areas, pitfalls, exam traps and key numbers.
What the calculation still does not answer
Before moving from £360,000 to advice, investigate the structure of the need.
Capital or income?
The mortgage and immediate reserve are capital needs. The £300,000 income figure represents a stream of household spending. A lump sum can meet that stream, but it introduces investment, withdrawal and longevity assumptions. An income-style benefit may match the need differently. The right answer depends on the client circumstances, not on which policy produces the neatest number.
Level or reducing need?
A repayment mortgage normally falls over time, while education and household spending follow different patterns. One level figure may overstate some future needs and understate others. Separating the components makes the recommendation easier to justify and review.
Is the replacement period defensible?
Ten years is an assumption, not a law. Link the term to the child’s dependency, the survivor’s work plans, retirement timing and other relevant facts. If the plan relies on the survivor returning to full-time work, record when and why that is realistic.
Is existing cover dependable?
Check the policy term, insured life, ownership, beneficiary arrangements and any relevant exclusions. Employer cover is valuable but may end when employment ends. A plan that depends heavily on it should explain the consequence of changing jobs.
Can the client afford the solution?
A technically complete package that cannot be maintained is not suitable. Prioritisation may be necessary: protect the most damaging risks first, compare structures and record any deferred need rather than pretending it has been solved.
Stress-test the answer
One useful exam habit is to change a single assumption and explain the direction of the result.
| Change | Likely effect on shortfall | Reason |
|---|---|---|
| Income-replacement period rises from 10 to 15 years | Increases | More years of spending need funding |
| Survivor’s reliable earnings increase | Decreases | Less household income needs replacing |
| Death-in-service cover ends after a job change | Increases | A current resource disappears |
| Mortgage is partly repaid | Decreases | Lower immediate capital need |
| Savings are reallocated to an inaccessible long-term goal | Increases | They should no longer be counted as available protection resources |
This is more valuable than memorising one “correct” cover multiple. The calculation should respond logically when the client facts change.
Six common exam traps
- Mixing events. A policy benefit available on death may not be available on incapacity.
- Mixing periods. Convert monthly and annual figures before comparing them.
- Mixing gross and net amounts. Match the income basis to the expenditure basis.
- Double counting. Do not include both the current value and death proceeds of the same arrangement in one death scenario.
- Treating illiquid wealth as cash. State how and when an asset could meet the need.
- Jumping straight to a product. Establish and prioritise the need before selecting the solution.
A reusable answer structure
For a protection scenario, write your reasoning in this order:
- identify the event and date;
- quantify capital needs;
- quantify the income gap and term;
- identify genuinely available resources;
- calculate the shortfall;
- test assumptions and affordability; and
- compare suitable benefit structures, implementation and review.
The wider CISI Financial Planning and Advice exam guide maps this technique to the current syllabus weights and 140-hour plan. For the official learning objectives applying to your sitting, use the current CISI Financial Planning and Advice syllabus and check the CISI Candidate Update page before the exam.
The central lesson is simple: calculate for a defined event, count only usable resources and keep the calculation separate from the recommendation. That produces both a stronger exam answer and a more defensible planning process.
Frequently Asked Questions
1 How do you calculate a protection shortfall?
Define the event, total the needs created by that event, subtract resources genuinely available at that time, and test the resulting gap against affordability, term and product suitability.
2 Should every asset reduce the protection gap?
No. Include an asset only if it is available in the scenario, sufficiently liquid and genuinely intended for that need. Do not count the family home as spendable capital unless a realistic release plan exists.
3 Can death-in-service cover be included?
It can reduce a current death shortfall when it applies, but its link to employment must be recognised. A recommendation should consider what happens if the client changes employer or loses the benefit.
4 Is the largest calculated policy always the most suitable recommendation?
No. The calculation establishes a need, not the final product. Affordability, term, ownership, existing cover, exclusions, flexibility and the form of benefit still need to be assessed.
5 What is the main CISI FPA exam trap in protection calculations?
A common trap is mixing unlike figures: monthly and annual cash flows, gross and net income, or current asset values and death benefits from the same contract. State the scenario, date and units before calculating.
Ready to Prepare for Your Exam?
Prepare with syllabus-aligned study tools, realistic practice and course-grounded AI support.
Explore Courses