Table of Contents
- • Compare the three routes
- • Step 1: recognise the complaint
- • Step 2: place the complaint on the correct timeline
- • Step 3: decide whether FOS is the next route
- • Step 4: test whether FSCS is relevant
- • A decision tree for exam scenarios
- - A. Is the business still operating and able to investigate?
- - B. Is the customer disputing the firm’s conduct or decision?
- - C. Is the alleged loss simply investment performance?
- • Four worked scenarios
- - Scenario 1: unsuitable advice, solvent firm
- - Scenario 2: authorised adviser has failed
- - Scenario 3: portfolio falls with the market
- - Scenario 4: complaint received but not labelled
- • Common CISI RPI traps
- • Final memory framework
CISI UK Regulation and Professional Integrity
Explore the study tools and practical exam preparation built for this course.
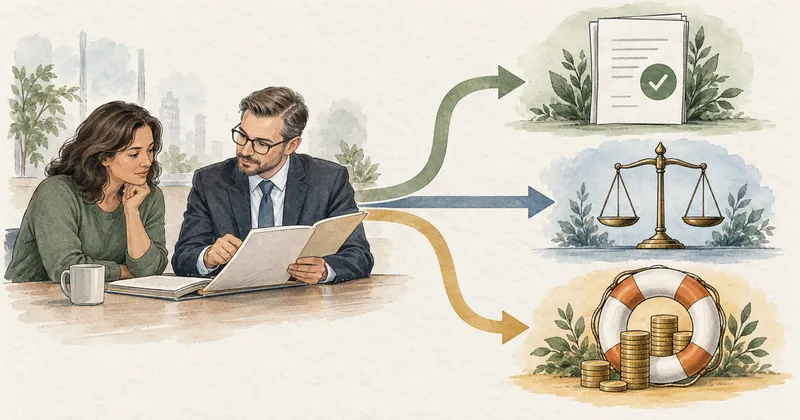
The firm’s complaints process, the Financial Ombudsman Service (FOS) and the Financial Services Compensation Scheme (FSCS) all protect consumers, but they solve different problems. CISI UK Regulation and Professional Integrity questions often become easy once you identify two facts: is the firm still able to respond, and is the issue a dispute or an unpaid protected claim following failure?
Shortest distinction: the firm investigates first; FOS resolves eligible disputes; FSCS may compensate eligible protected claims when a firm cannot meet them.
Compare the three routes
| Route | Main purpose | Typical trigger | What it is not |
|---|---|---|---|
| Firm complaint process | Recognise, investigate and resolve dissatisfaction fairly | Customer alleges financial loss, material distress or material inconvenience | An optional customer-service gesture |
| FOS | Independently resolve an eligible dispute | The customer is dissatisfied with the final response or the relevant response period has expired | The FCA, a court or an insolvency compensation fund |
| FSCS | Provide last-resort protection for eligible claims | An authorised firm is unable, or likely unable, to meet a protected claim | A guarantee against market loss or poor performance |
Do not choose a route merely because the scenario contains the words “compensation” or “complaint.” Identify the status of the firm, the nature of the loss and the procedural stage.
Step 1: recognise the complaint
A complaint is identified by its substance, not its format. It can be oral or written and does not need to use the word “complaint.” A relevant expression of dissatisfaction may allege financial loss, material distress or material inconvenience.
The firm should:
- recognise and record the complaint;
- investigate competently, diligently and impartially;
- assess the facts, relevant rules, law, contract, guidance and good practice;
- communicate clearly and keep the complainant informed;
- provide appropriate redress or remedial action where due; and
- examine root causes and whether other customers may have suffered similar harm.
Paying one customer without investigating a recurring control failure is not a complete response.
Step 2: place the complaint on the correct timeline
For an ordinary complaint, a firm generally has eight weeks to send a final response or a compliant explanation of why it cannot yet do so. A complaint resolved by the close of the third business day following receipt can use the summary-resolution route with the required FOS information.
Payment-service and e-money complaints have a different timetable: certain complaints normally require a response within 15 business days, with a final response within 35 business days where the permitted exceptional delay applies.
The FCA consumer complaints guide explains the practical sequence. For exam questions, distinguish three separate clocks:
- the firm’s response deadline;
- the underlying complaint time test, normally six years from the event or, if later, three years from awareness; and
- the usual six months from the final response for referral to FOS.
These periods answer different questions. Do not add them together or substitute one for another.
Step 3: decide whether FOS is the next route
FOS may be the next step when the complaint is within its jurisdiction and either:
- the firm has sent a final response and the complainant remains dissatisfied; or
- the applicable response period has elapsed without a final response.
FOS is independent and decides what is fair and reasonable in the circumstances. It can make monetary awards and directions within its powers. If the complainant accepts an ombudsman’s final decision, it becomes binding on the business.
FOS does not authorise firms, write prudential rules, prosecute financial crime or act as the compensation fund for an insolvent business. The detailed eligibility and jurisdiction tests still matter; “the customer is unhappy” does not automatically place every dispute within FOS.
Free CISI UK Regulation and Professional Integrity Practice Questions & Exam Preview
Try 15 CISI UK Regulation and Professional Integrity practice questions from Element 5: The Regulatory Framework relating to Financial Crime
Practice CISI UK Regulation and Professional Integrity exam questions with answers and explanations. The full course includes 5 mock exams and complete syllabus coverage.
Exam Preview
A trader places orders intended to create a false impression of demand, then cancels them. Can market-abuse rules be relevant without a completed trade?
Flashcards
A bank's solvency is deteriorating. Why is a conduct-only response insufficient?
Focus Learn
- Primary and secondary markets
- Government and the economy
- Consumer needs and financial planning
- FCA conduct and prudential remit
- PRA microprudential supervision
- Capital, liquidity and prudential frameworks
- Supporting public bodies
- Governance, compliance and assurance
This chapter covers the role of government, market structure, UK financial-services and consumer relationships, and the regulatory infrastructure. Government affects economic activity through policy, regulation, taxation, social welfare and its relationship with the wider economy. Fiscal policy concerns taxation, public borrowing and public spending. Monetary policy concerns the money supply and interest rates and is implemented through the Bank of England framework. These tools can affect growth, inflation, employment, borrowing costs and investment markets, but a policy aimed at one objective can affect another.
Primary markets are the route through which issuers raise new capital by issuing securities. Secondary markets allow investors to buy and sell securities that have already been…
Unlock all Focus Learn
Open every chapter’s key areas, pitfalls, exam traps and key numbers.
Step 4: test whether FSCS is relevant
FSCS becomes relevant when a firm is unable, or likely unable, to meet an eligible protected claim. Work through the sequence:
- Was the provider or adviser appropriately authorised?
- Is the service or product within a protected category?
- Is the claimant eligible?
- Is there a valid claim rather than an ordinary market loss?
- Is the firm unable, or likely unable, to meet the claim?
- Which category and limit apply?
For investments, FSCS states that eligible claims can be protected up to £85,000 per person, per firm. It also makes clear that poor investment performance is not itself compensable. Deposit, insurance, home-finance and investment claims have different rules and limits, so do not transfer one category’s number to another.
Authorisation alone does not promise compensation. The activity, product, claimant and claim must all fall within the relevant protection rules.
A decision tree for exam scenarios
Use these questions in order:
A. Is the business still operating and able to investigate?
- Yes: start with its complaints process.
- No or likely unable to meet liabilities: consider whether an eligible protected FSCS claim exists.
B. Is the customer disputing the firm’s conduct or decision?
- Yes: after a final response or expiry of the response period, consider FOS jurisdiction and time limits.
- No: identify whether the scenario concerns a regulatory report, court action, insolvency claim or another route.
C. Is the alleged loss simply investment performance?
- Yes: FSCS does not compensate a normal fall in investment value.
- No: ask whether bad advice, mismanagement, missing assets or another protected civil liability exists and whether the failed firm can meet it.
Four worked scenarios
Scenario 1: unsuitable advice, solvent firm
A customer says a solvent advisory firm recommended a product inconsistent with her capacity for loss. The immediate route is the firm’s complaint process. If she remains dissatisfied after the final response, or the relevant response period expires, FOS may be considered. FSCS is not the first answer merely because she seeks money.
Scenario 2: authorised adviser has failed
A customer has a valid claim for loss caused by protected investment advice, but the authorised advisory firm is in default and cannot pay. FSCS may be relevant, subject to eligibility and the investment limit. FOS is not the fund that pays claims against failed firms.
Scenario 3: portfolio falls with the market
An investor loses money because markets decline, with no evidence of bad advice, mismanagement or missing assets. Poor performance alone is not an FSCS claim. The existence of an authorised firm does not insure investment returns.
Scenario 4: complaint received but not labelled
A customer phones to say repeated administrative errors caused financial loss and distress, but never says “I want to complain.” The firm should recognise the substance and apply its complaints process. Requiring a formal label would be a barrier, not a valid reason to ignore the issue.
Common CISI RPI traps
- FCA versus FOS: the FCA regulates; FOS resolves eligible disputes.
- FOS versus FSCS: FOS decides disputes; FSCS protects eligible claims following firm failure.
- Authorised means every loss is protected: authorisation is necessary in many cases but not sufficient.
- A complaint must be written: substance, not channel, identifies it.
- Eight weeks means the firm may ignore the customer: firms should investigate and communicate promptly; eight weeks is not a service target.
- Six months replaces the six-year/three-year test: the post-final-response deadline and underlying complaint time test are separate.
- A payment ends the matter: root-cause analysis and wider remediation may still be necessary.
Final memory framework
Remember resolve, decide, protect:
- the firm resolves the complaint first;
- FOS decides eligible unresolved disputes; and
- FSCS protects eligible claims when a firm cannot pay.
The broader CISI UK Regulation and Professional Integrity preparation guide covers all six current syllabus elements and the 140-hour plan. Use the current FCA complaints guidance, FOS information and FSCS protection pages to verify live consumer procedures and limits rather than relying on an undated summary.
Frequently Asked Questions
1 What is the simplest difference between FOS and FSCS?
FOS independently resolves eligible disputes between customers and financial businesses. FSCS is a fund of last resort for eligible protected claims when an authorised firm is unable or likely unable to meet them.
2 Does a customer normally complain to the firm before going to FOS?
Yes. FOS can normally consider the case after the firm sends a final response or after the applicable response period has elapsed. Ordinary complaints generally use an eight-week period, with different payment-service and e-money timelines.
3 Does FSCS compensate poor investment performance?
No. Market loss or poor performance is not enough. Eligibility depends on factors including the authorised firm, protected activity, valid claim and the firm's inability to meet the claim.
4 What is the usual deadline for referring a complaint to FOS after a final response?
The usual deadline is six months from the firm's final response, subject to the detailed rules and exceptions. This is separate from the six-years-or-three-years complaint time test.
5 What is the current FSCS investment protection limit?
FSCS states that eligible investment claims can be protected up to £85,000 per person, per firm. Coverage is not automatic and does not include ordinary poor investment performance.
Ready to Prepare for Your Exam?
Prepare with syllabus-aligned study tools, realistic practice and course-grounded AI support.
Explore Courses